Playback starts YouTube’s embedded player (privacy-enhanced mode).
How to Calculate Value at Risk (VaR) Using Excel || Value at Risk Explained
ChannelMatt MacartyChapters
Description from the creator
@MattMacarty
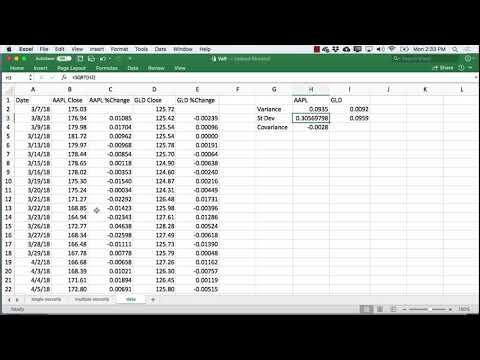
**Master the calculation of Value at Risk (VaR), the essential statistical measure of downside risk.** In this advanced financial modeling tutorial, we demonstrate the **Parametric VaR** method using the Normal Distribution to estimate the maximum potential loss over a specific time horizon and confidence level.
We cover both single-security VaR and the more complex multi-asset VaR, using portfolio volatility as the core input.
---
### ⏱️ Video Chapters / Timestamps
0:00 - Introduction: What is Value at Risk (VaR)?
0:31 - Non-Parametric vs. Parametric VaR methods
1:00 - The required inputs: Portfolio Value, Volatility, Time Horizon, and Confidence Level
1:47 - The problem with VaR: What happens beyond the confidence level?
2:42 - **Example 1: Single-Security VaR (Apple)**
3:30 - Using the **`NORMS.INV`** function to find the confidence Z-score (2.33 standard deviations)
4:05 - Calculating Single-Day and Multi-Day VaR
5:15 - **Example 2: Multi-Security VaR (Apple & Gold)**
5:46 - Calculating Portfolio Volatility for two securities (Manual formula)
6:55 - The full portfolio volatility formula explained
7:35 - Risk reduction benefits from diversification
7:52 - Final Multi-Asset VaR Calculation
8:45 - The need for Matrix Math in larger portfolios (10+ assets)
---
### 🔎 Summary of Skills Learned
* **Theory:** Understand the statistical assumptions of Parametric VaR (Normal Distribution).
* **Functions:** Learn to use the `NORMS.INV` function in conjunction with the standard deviation.
* **Application:** Calculate a 99% confidence VaR for both a single stock and a diversified portfolio, while correctly adjusting the volatility for the time horizon using the square root rule [04:17].
---
Get vidIQ to grow your channel faster! 🚀
vidiq.com/alphabench
About this tutorial
Matt Macarty published this 9:36 video tutorial on November 8, 2019. It has been watched 90,147 times on YouTube.
- Channel
- Matt Macarty
- Category
- Education
- Duration
- 9:36
- Published
- November 8, 2019
- Views
- 90,147
- Likes
- 682
Tags
Share
This tutorial in other languages
- FRComment calculer la valeur à risque (VaR) En utilisant Excel || Value at Risk Explained
- ES¿Cómo calcular el Valor en Riesgo (VaR) Uso de Excel || Explicación Valor en Riesgo
- PTComo Calcular Valor em Risco (VaR) Usando Excel || Value at Risk Explicada
- ITCome Calcolare Value at Risk (VaR) Utilizzo di Excel || Value at Risk Explained
- DEWie berechnen Value at Risk (VaR) mit Excel || Value at Risk Explained
- NLHoe te berekenen Value at Risk (VaR) Met behulp van Excel || Value at Risk Explained
- RUКак рассчитать стоимость, подверженная риску (VaR) Использование Excel || Значение в опасности Разъяснения
- PLJak obliczyć wartość zagrożona (VaR) za pomocą programu Excel || Value at Risk Poradnik
- JAどのように計算した値にExcelを使用してアットリスク(VaR)||アット・リスク値の説明します
- ARكيفية حساب القيمة المعرضة للخطر (VAR) باستخدام إكسل || القيمة المعرضة للخطر شرح
- HIकैसे की गणना करने के लिए मूल्य रिस्क (वीएआर) पर एक्सेल का उपयोग करना || जोखिम में मूल्य समझाया
- IDCara Hitung Value at Risk (VaR) Menggunakan Excel || Value at Risk Dijelaskan